Showing posts with label New South Wales. Show all posts

Monday, 12 October 2026

NSW Parliament publishes report into forthcoming road user charge for electric vehicles

New South Wales (NSW) looks set to be the next jurisdiction to implement a distance-based road user charge (RUC) on electric and plug-in hybrid light vehicles, from 1 July 2027.  From that date, EV owners will be subject to a charge of A$0.03095/km (US$0.0347/mile) and PHEVs A$0.02476 per km (US$0.0278/mile). It won't be the first in Australia to do so, as the state of Victoria implemented RUC on EVs and PHEVs in 2021, but this was cancelled in 2023.

The Parliament of NSW has now published a report into the forthcoming RUC.

Background

In Australia, RUC is a complex topic. For years the Commonwealth (Federal) Government studied and even piloted distance/weight based RUC for heavy vehicles, largely because multiple reports indicated that there would be economic productivity benefits from introducing it, alongside a wide range of associated funding and charging policy measures.  In the meantime, heavy vehicles pay registration fees to the States and Territories, at unified rates, and when paying fuel excise duty on diesel, they can claim a 100% refund for diesel not used on public roads and a partial refund of the remainder (with the part that is retained called the "fuel based road user charge"). Since 2024, heavy vehicle RUC has largely been off the political agenda in Australia. 

Then came electric vehicles (EVs), in sufficient numbers that it started to be a concern for future fuel excise duty revenues. Fuel duty is a Commonwealth tax (the States and Territories are not constitutionally permitted to levy such a tax), but is not hypothecated. States and Territories started being interested in whether they could charge a RUC for light EVs, so Victoria did so in 2021, only for a court case to go as far as the High Court of Australia, which struck it out as unconstitutional in 2023.  That court case was supported (but not led) by the Commonwealth Government. I wrote about the decision (known as Vanderstock) at the time, as I agree with the dissenting opinions of the court.  It was quite the stretch of interpretation to treat the Victorian RUC as an "excise tax" that influences the supply of electric vehicles (and therefore only within the Constitutional scope of the Commonwealth Government), but the decision stands.  

However, parallel to Victoria, the NSW Government passed the Electric Vehicles (Revenue Arrangements) Act 2021, with nearly identical language to the legislation used in Victoria.

That Act means that from 1 July 2027, EVs in NSW will be subject to a distance based RUC.

The obvious conflict is that the Vanderstock decision essentially indicated that RUC should be implemented nationally by the Commonwealth Government, not by the states. but since the decision there has been relatively little said at the Commonwealth level about RUC. 

A series of statements have been made by a few Ministers ranging from how important it is to charge EVs for road use eventually, to concern that legislation to enable this might not get passed by the Senate. 

While there has been some work behind the scenes undertaken by officials, no decisions have yet been made. Meanwhile, sales of EVs in Australia (as in many countries) are at a record high. In the year to August 2026. 18.5% of new light vehicle sales in Australia have been EVs, with it being over 26% in the month of August alone. 

NSW's legislation has not been amended or repealed (although the election in 2023 saw a change in State Government from the Liberal/National Coalition to Labor). 

Public Accountability and Works Committee

Earlier this year, the NSW Legislative Council delegated to its Public Accountability and Works Committee a review into the operation of the Act, and in particular:

(a) whether the policy objectives of the Act remain valid, and

(b) whether the terms of the Act remain appropriate for securing those objectives. 

It undertook its inquiry and has now published its report and recommendations.  Most of the ten recommendations should not be a particular problem to implement. Two of them are not good ideas, but not impossible to implement.

The NSW Government needs to respond to the report by January 2027, which gives essentially no time to amend the legislation, especially since on 13 March 2027, there is a state election. 


Report details

I’ve read more than a few reports from elected committees about various forms of road user charging and road pricing over the years, and I’m glad to say this is one of the better ones. By and large, most of the conclusions drawn are at least practical, and have some rational public policy basis for them, although a handful of them are not. 

The report is overall positive and supportive of the implementation of RUC for EVs in NSW, notwithstanding some concerns.  

Issues considered in the report include:
  • Implications of the Vanderstock High Court of Australia decision on the legislation, including possible amendments to distinguish the NSW proposal from the Victorian policy
  • Effects on EV sales
  • Impacts of distance based RUC on different geographical communities and vehicle operators including rideshare, delivery drivers and dealerships
  • Impacts on plug-in hybrid drivers
  • Merits of pure distance based RUC vs including weight, fuel efficiency and congestion
  • Hypothecation of net revenues
  • National RUC for EVs vs. states going first
  • Administration of a RUC
I won't summarise the whole 88 page report here, but it is worth a read (PDF). 

The concerns expressed are understandable and not unreasonable. It is worth noting that the Committee was chaired by a Green MLC (Member of Legislative Council), with the deputy chair from the Liberal Party.  Besides them, there were three Labor, one National and one independent (Mark Latham) on the Committee. Only Latham made a dissenting statement, and that was to support weight based vehicle registration for EVs as an alternative.

A key recommendation was to proceed, regardless of progress at the federal level, which I believe is sound, albeit risky.

At the very least, it is clear that States and Territories could wait for a national RUC system and still be waiting one, two, three or even five years from now, mainly because the political will to proceed is tepid at best. That may be proved wrong in the coming months, but it is more likely than not that NSW pushing on with RUC will catalyse action from the Commonwealth Government which is more rapid than simply waiting for something that shows few signs of progressing fast.

I have summarised the recommendations below with comments in italics.

Recommendations

Recommendation 1
That the NSW Government ensure that any future road user charge for electric vehicles is designed and operationalised in a way that does not dampen or impede the uptake of electric vehicles in New South Wales.

Understandable, and easy to address. The basis for this was evidence that RUC when introduced in Victoria and applied to EVs in New Zealand, had no apparent impact on sales. Evidence in New Zealand is blurred by the removal of a major subsidy scheme that saw levies on some new cars used to subsidise the sales price of low emission ones.  That brought forward EV sales, and meant that when RUC was applied to EVs in mid 2024, there was no effect on sales. There remains scant evidence that charging a few cents per kilometre for road use deters a purchase of an EV compared to a ICE vehicle that is already charged the same or more through fuel tax.

Key to complying with this recommendation is perhaps two elements:
  • Ensuring administration and compliance for RUC for EVs is simple with minimal friction for owners. It should be easy to buy, have distance reported and be compliant, without prospective EV owners fearing not being able to understand or being fined inadvertently for getting it wrong.  There are plenty of models for doing this  - see New Zealand, Hawai'i and Oregon.
  • Setting a rate for RUC, for now, that is cheaper than fuel excise.  A rate commensurate to around half of the average paid by a light ICE vehicle may be appropriate, not least because it would around the same for a battery-electric hybrid vehicle.  The proposed A$0.0395/km seems like it would do that. 
Recommendation 2
That the NSW Government, in consultation with industry stakeholders, monitor the implementation of any future road user charge for electric vehicles in New South Wales with a view to:
• assessing any impact on electric vehicle uptake, and
• promptly identifying other unintended consequences that would undermine the strategic transition to electric and low emissions vehicles.

Agree. There is considerable merit in undertaking impact monitoring, perhaps for the first two years, of RUC on sales and any unintended consequences on users.  Related to this is having flexibility to make regulatory changes at short notice to address any of these, and to take lessons from other jurisdictions about what to avoid (e.g. avoid over-complicating the passage of liability of RUC on vehicle sale or vehicle scrappage).

Recommendation 3
That the NSW Government consider an electric vehicle road user charge exemption for registered dealers of new 'in scope' low and zero emissions vehicles, to be applied up to a prescribed number of kilometres travelled on demonstrator models, and that the threshold be determined in consultation with industry stakeholders.

Disagree.  The objective of this appears linked to Recommendation 1, but this is not a good idea. The best time to educate vehicle owners about RUC is when they purchase a vehicle new.  This appears to be a call for a subsidy for new EVs, when similar exemptions don't exist for fuel duty or even tolls.  It is likely to mean "demonstrator models" get used more by proprietors and staff of dealerships, and then when sold it is a transfer from taxpayers to buyers of those vehicles. 

No other jurisdiction does this (noting Victoria had such a provision). In New Zealand, dealerships buy a block of RUC distance in advance and it is effectively included in the sales price. There is no great burden in having newly registered vehicles including a prepaid block of RUC kilometres, which is essentially like fuelling the vehicle. By contrast, in Oregon the initial OReGO program did not make provision for dealerships to offer RUC to vehicle owners, so they needed to be followed up around a year later to get enrolled with RUC or pay a higher annual registration fee. This is now being amended.

Recommendation 4
That the NSW Government consider hypothecating the future revenue collected under the Electric Vehicles (Revenue Arrangements) Act 2021 towards road maintenance and infrastructure.

Agree. This will help differentiate the RUC from the Victorian programme, but also allow for charges to be more closely linked to what is spent on the network, treating roads as a network utility. This could be done notionally, matching the net revenue collected to a specific allocation of funds for roads maintenance, or more formally (which would progressively grow in scale as RUC expands).  Treasuries hate hypothecation because they want maximum flexibility over the use of tax revenue, but if NSW's RUC is to be treated not as a tax, but as a user fee, it should have a relationship to what is spent on the network.  Furthermore, it is more likely to obtain public acceptability, if it is not treated as just another new source of revenue.  I'll note that the now virtually stalled Heavy Vehicle Road Reform programme includes hypothecation for a future national heavy vehicle RUC.

Recommendation 5
That the NSW Government investigate fairer distance-based options for electric vehicle road users in rural, regional and outer suburban communities and light commercial vehicle operators without creating loopholes or adding to the administrative burden or complexity for drivers.

Agree, pending clarification of the problem.  The report assumes that people living in rural, regional and outer suburban communities drive more distance in aggregate on average, than those in inner city communities. There is no evidence provided to support this. I'll note that in the United States, RUC America undertook a study comparing the impacts of introducing distance-based RUC to replace fuel excise for people in urban vs. rural locations and it was published in 2022. It concluded that in many cases people in rural areas did NOT drive greater distances, because they drove less frequently than residents in urban areas. Similar research in NSW would be informative and useful.

Some of the commentary in the report around delivery and gig worker drivers seems to ignore that such drivers face these fees now with ICE vehicles, paying fuel duty for driving more.  Research might indicate that delivery drivers pay more in fuel duty per kilometre driven than the average, because of the amount of starting and stopping compared to private vehicle trips. It seems particularly questionable to want to cap what is charged for such vehicles, when EVs are likely to deliver considerable savings in energy costs already.

Notwithstanding this, there is merit in enabling the registration and certification of third-party service providers to collect RUC using telematics systems either as equipment already installed in vehicles or third-party devices, to measure distance by location. This would enable exemption of distance travelled off public roads and out of state, and for measurement to be automated.  This could provide options for rural drivers and drivers located in border communities to avoid paying for travel in adjacent States and Territories. Note that Vermont has agreed to implement RUC for EVs, but requiring such an option be implemented two years later.

Recommendation 6
That the NSW Government amend the Electric Vehicles (Revenue Arrangements) Act 2021 to reframe the road user charge to have the character of a licence fee or fee for service, rather than a tax or excise.

Agree, noting that the timing to do this seems challenging at best. It should be a user fee for the use of public roads in New South Wales, and it could include a means to grant refunds for distance off of public roads or in other states, if evidence is given of proof of such travel. This could only be done after the event, and have an administrative cost to it.

Recommendation 7
That the NSW Government amend the Electric Vehicles (Revenue Arrangements) Act 2021, or use future regulations or any other appropriate mechanism, to introduce a differentiated distance-based regime in which the per kilometre rate takes into account:
• a vehicle's size and weight
• differences in battery performance and life for battery electric vehicles
• differences in emissions performance among low-emissions hybrid vehicles.

Disagree. This appears to be based on a misperception as to wear and tear on road surfaces generated by variations in weight among light vehicles. This is not supported by research commissioned by the National Transport Commission or seen overseas. Beyond the impacts of weather, there is very little impact of vehicle weight on road maintenance below the level of heavy vehicles (GVM >4.5 tonnes).  Note New Zealand did use to charge light vehicles at one tonne intervals, with the rates varying by a tenth of a cent per kilometre. One tonne increments were scrapped for light vehicles some years ago to simplify administration.

The proposal to charge differently according to battery performance and life are highly problematic not least because such data is not collected in the motor vehicle register. It would be difficult to measure this and unclear the basis for varying charges, particularly as performance and battery life varies over time.  The proposal to take into account emissions performance among hybrid vehicles (which in this case would be plug-in hybrids) also has problems around getting a reliable source of data to classify vehicles, and to incorporate it into the motor vehicle register.  It is common to charge vehicles differently by Euro class, in heavy vehicle RUC systems in Europe, but that is for vehicles almost all of which are powered by diesel.

The relative impacts and merits of such proposals seem likely to be not worth the cost and complexity to implement.

Recommendation 8
That, with respect to the administrative arrangements to operationalise any future road user charge, the NSW Government commit to:
• keeping it as simple as possible for drivers to minimise the administrative burden
• fully integrating the charge within the existing administrative scheme for vehicle stamp duty, registration fees and licensing.

Agree. There should be a base level simple product for vehicle owners to interact with, such as a prepaid licence (as in New Zealand), an annual fee based on an estimate confirmed at registration time, or a regular invoice based on an average or submitted distance. It makes perfect sense to integrated with registration fees, but there needs to be a rapid commitment to the base level product that provides the most flexibility to users, while enabling alternatives either immediately or within a couple of years.

Recommendation 9
That the NSW Government continue to work with the Federal and state governments on road user charging policy, with a view to working towards a national road user charging system.

Agree, it should go without saying that a national system or nationally co-ordinated system is preferable to a patchwork of policies that risk incoherence.

Recommendation 10
That, absent a national road user charging framework and regime, the NSW Government proceed to implement the electric vehicle road user charge established by the Electric Vehicles (Revenue Arrangements) Act 2021 subject to the amendments outlined in Recommendations 1 to 8 above.

Agree.

Next steps

The NSW Government is expected to provide the Government Response to this report by 11 January 2027.  This should give a clear indication of what happens next.

In the meantime, it is not impossible to expect that there might be an announcement from the Federal government in Canberra about RUC policy nationally (although few would bet on it). The Mid-Year Economic and Fiscal Outlook is due to be issued in December 2026, which would cut it fine indeed, but be timely to signal what might happen nationally.  However, it is also quite likely that nothing will be signalled, given other government priorities.

Friday, 14 August 2026

NSW advances toll reform

Tolls have been a major political issue in New South Wales (NSW) for some years, or rather (I should say), Sydney.

It is sometimes claimed (including by the NSW Government) that Sydney has the greatest number of toll roads of any city in the world. That's not true. While it has 156km of toll road, Tokyo easily has over double that as does Dallas/Fort Worth (which has about the same length of full toll roads as Sydney, but the same again in tolled lanes/HOT lanes on otherwise untolled roads). Santiago, Chile has over 200km of tolled roads, as does Osaka, Japan.

Of course Sydney does have the longest length of toll roads of any city in Australia. Brisbane has around 90km and Melbourne 78km (although North East Link will add another 10km), so Sydneysiders may feel it is unfair, but Sydney has a lot of toll roads because its geography

Sydney's toll road network is impressive, but toll rates are un-coordinated. The map below depicts the tolled road segments only.

Sydney toll road network

The Independent Toll Review for the NSW Government, released two years ago and led by Professor Allan Fels (former Chairman of the ACCC) as Independent Chair with Dr David Cousins as Deputy Chair, proved controversial, especially with toll road concessionaires.

I wrote about it in three parts: Background, Findings and Recommendations. in 2024. 

It is telling that it has taken so long for the NSW Government to determine what was feasible—not merely politically and legally, but commercially—given that most of the state’s toll roads are locked into PPP concessions. This is a legacy of successive Coalition and Labor governments (it is simply not true that the results are just because of the Coalition's "privatisation" policies, when Labor embarked on multiple toll road concessions itself), and simply reflects the rather ad-hoc development of Sydney’s tolled motorway network over the past thirty years. Those concessions have locked in toll rates and, in particular, complex and expensive-to-renegotiate price escalations.

Notwithstanding these constraints, the NSW Government retains some flexibility. It owns two key toll roads (the Sydney Harbour crossings) and can negotiate with concessionaires. Some concessions are coming to their end.

It is therefore a relief that decisions on toll reform have finally been made. While some may argue that the measures only scratch the surface, they represent a step forward.Note that Transurban, as the sole or part owner of virtually all the concessions in Sydney, is also publicising its role in the negotiations. So what is going to occur?

There are 12 toll roads in Sydney (if you count the Military Rd E-Ramps as being associated with the Lane Cove Tunnel), so the impacts vary across the roads.

The official NSW government information on the reforms is here.

Transurban has also published its own press release about the reforms. Transurban says it has been working constructively to enable tolling reform and its own website is replete with useful information. Of course Transurban is, legally and commercially, focused on protecting and enhancing its own profitability, but that also requires ongoing social licence and political acceptability. It's a careful balance for a business that perhaps thought itself somewhat under siege during the Independent Toll Review and understandably so, particularly given its long term interest in protecting its position as lead toll concessionaire and operator for existing (and future) toll roads.

I haven't sought to detail all of the changes, just the main ones.

Tolls reduced or toll increased reduced

Four roads see tolls reduced for most users:

  • Lane Cove Tunnel (10%)
  • M2 (longer trips only) (10%)
  • M7 (10% lowering of the distance cap)
  • Cross City Tunnel (20% reduction when Western Harbour Tunnel opens).
The Sydney Harbour Bridge and Tunnel toll increases, which were to be 4% are now going to be at 3.25%.

Change vehicle class multipliers

Heavy vehicle multipliers on Sydney toll roads have varied from 2x to 3.47x the standard light vehicle rate. From 1 July 2027, all (except the Lane Cove Tunnel) will be standardised at 3.15x.  This both simplifies tolls for trucks, but also ensures demand by heavy vehicles is more evenly spread between toll roads and untolled roads.  For example, the Eastern Distributor is cheaper than the M7, effectively encouraging more truck traffic through that central corridor, compared to the M7/M2 corridor.

The other adjustment is to implement a 0.5x multiplier for motorcycles. This is a reduction for all roads, recognising that motorcycles occupy much less road space (and should encourage more use by motorcycle owners).

Two way tolling

This had already been agreed for the Sydney Harbour Bridge and Tunnel, so that tolling will be northbound as well as southbound, which will better regulate demand on both crossings. especially with the imminent opening of the Western Harbour Tunnel. 

Two way tolling will also be implemented on the Eastern Distributor, once the Western Harbour Tunnel is opened. With the toll in each direction being 53% of the current one way (northbound) rate, this should also better regulate the flow of traffic in both directions on this corridor, and more importantly across the harbour.

Other measures

The press release indicates that toll concessionaires will pay A$75m over five years to help pay for the weekly toll cap, which is a recognition that it will increase demand on their roads.

The remaining two-lane each way (four lane) sections of the M7 and M2 motorways (Richmond Road to Old Windsor Road) will be widened, at taxpayer expense without a toll increase or extension of the private concessions.

The weekly toll cap will continue. It means that a NSW resident with a personal toll account (such as Linkt or E-Toll) and a privately registered vehicle is subject to a cap of A$50 per week in tolls.  It works through lodging a claim for the excess quarterly through Service NSW.

The M5 Cashback programme will also continue (although you cannot use both the cap and the cashback on the same road. M5 Cashback effectively means M5 toll road users, registered with private vehicles in NSW, can claim back the toll quarterly. 

Conclusions

It was hard to negotiate any changes with concessionaires, but from an economically rational point of view, several of the announced measures are a step forward.

Standardising vehicle class multipliers makes a lot of sense. For toll roads the multipliers should mostly reflect road space occupancy (and the capital of the capacity built to take the vehicles).  

Two way tolling is more rational than one-way, particularly when there are alternative routes that see some southbound traffic use the Gladesville and Iron Cove Bridges, then the Anzac Bridge, to avoid tolls. Moving to two way tolls should rebalance those flows. 

Everything else appears to be a subsidy or a cap on tolls charged. There is a point to capping or discounting heavy use of toll roads, as frequent users are undoubtedly over contributing towards the costs of that infrastructure, but blanket caps on private users and the M5 cashback subsidise demand.  There might be a point to capping off-peak use, but there is nothing here about charges varying by time of day.

Sydney Harbour Crossings have peak, shoulder and off-peak charges, but that's because they are not subject to a concession. Wider application of time of day varying toll charges would obviously have an impact on congestion and spread demand, but the chances of toll concessionaires agreeing to this with countervailing reductions in tolls over longer off peak periods appear to be next to zero. 

So a step forward? Yes.

Does it address all of the fundamental limitations and issues around tolling in Sydney? No. That will have to wait another day.

It's my view that the public image of tolls in Sydney is by far the single biggest barrier to any form of congestion pricing in the city. Quite simply, few believe that pricing roads leads them to flow better and be less congested, or that it isn't primarily about money.  Most cities that have introduced congestion pricing did not had tolls on any scale previously (Singapore, London, Stockholm, Gothenburg). 

The best hope for Sydney demonstrating congestion pricing in some way, in the medium term, is the state applying higher peak charges on the tolled routes it owns in exchange for cheaper off-peak charges (to encourage use of spare capacity). Perhaps once the Western Harbour Tunnel opens, and all harbour crossings are tolled two-way (once more), there may be more will to do this.

Monday, 10 February 2025

Australia and road user charging

It's pleasing to see Australian Federal Treasurer, Hon. Dr Jim Chalmers, be upfront about the need for Australia to introduce a road user charge (RUC) for electric vehicles as a "priority" tax reform, at a recent business dinner according to the Australian Financial Review.

None of this is new, as Australia has been down quite a tortuous stumbling path on reforming how motor vehicles are charged to use the country's roads for over a decade, depending on how you look at it.

This is distinct from tolling, which is used in three States for specific projects. It is NOT about that, but rather how roads are charged for across the entire network

Very brief history

Australia has been on a long, slow path to investigating and piloting RUC for heavy vehicles (defined in Australia as any vehicles with a GVM of 4.5 tonnes and above) for over a decade. The main reason being that the current system, of fuel tax (with a proportion deducted so that the remainder is a fuel based "road user charge" based purportedly on a cost allocation calculation), collected Federally with steeply escalating motor vehicle registration charges based on weight and configuration to attempt to make up the shortfall that fuel tax can't recover (and collected at State and Territory level), is less than optimal.  

The latest step in this policy process has been the National Heavy Vehicle Charging Pilot, which had its genesis multiple Ministers (and Prime Ministers) ago, under the Turnbull Government with Minister Paul Fletcher. That pilot has concluded and the results of the evaluation of the pilot have yet to be published, but there is little political focus on this, mainly because the issue it is trying to address is not a loss of revenue, but rather a poor link between what is paid to use the roads and the supply of roads.

That is addressed through a programme called Heavy Vehicle Road Reform, which has been moving glacially for some years.  Heavy Vehicle Road Reform contains all of the elements for a fundamental reform of how roads are charged for, funded and managed in Australia, but does require consensus between Federal and State/Territory Governments. It could be combined with agreement to progress road user charging for EVs, but they have generally been on a different track.

At least four Australian states advanced RUC for EVs to some level. South Australia, New South Wales and Western Australia all passed legislation to introduce it in a future year, but the South Australia legislation was repealed by a change in Government at the previous election. The New South Wales and Western Australia legislation remain intact for EVs to pay by distance from 2027.  Victoria introduced such a charge in 2021 only to have it overturned by a court decision ruling it unconstitutional in 2023, which raises big questions about whether the other states could implement such a charge themselves. 

That's the nexus of the current policy question is about what the Federal Government does to enable the implementation of RUC for EVs. It has choices ranging from implementing a Federal RUC to simply empowering the States and Territories to implement their own systems within a regulatory framework designed by the Federal Government.

The latter makes sense, but also presents a range of options around having a integrated set of incentives around implementing RUC, so that the Federal Government isn't simply handing over a revenue source (fuel tax for petrol and diesel vehicles at present, EV RUC for the future) to States and Territories unencumbered. 

I've already written about some of the issues that need to be thought about, and I think it requires a reset of the relationship between the Federal and State/Territory Governments on road funding, which can include heavy vehicles. That would mean the States and Territories accepting that they will not be responsible for collecting and spending all revenue from a future RUC, but also the Federal Government accepting some form of hypothecation for that revenue (which doesn't currently apply to fuel excise).

Every year RUC for EVs is delayed, it gets a little harder to implement because the constituency for it grows.  A Federal election is due in Australia no later than 17 May 2025. Hopefully, whichever party (or parties) forms the next Government will move quickly to establish a policy platform for RUC that should incentivise acceptance by States and Territories and enable progress for both light and heavy vehicles in the coming years.

Bearing in mind that in the US, there is considerable progress by many States and now the Federal Government in considering how to fairly charge for EVs and the transition away from fuel tax.  Meanwhile, New Zealand has had a RUC for over 40 years, recently extended to EVs and PHEVs (it has applied to light diesel vehicles for decades) covering over 1m vehicles all up, it should be possible for Australia to introduce, at least in the first instance, a basic national RUC charge equivalent to fuel duty (or better yet, based on a cost allocation approach), collected at State/Territory level.  

Monday, 29 July 2024

"Motorists First" - Findings of the Independent Toll Review for the NSW Government - Part Three: The Recommendations

Given the findings of the Independent Review, and particularly the highly controversial Interim Report (which essentially called for the NSW Government to legislatively override existing toll concession agreements, causing heart attacks at Transurban and among its investors), the recommendations to finally come out of this review are critical. However, equally critical is what, if anything, the NSW Government is going to do in response.

It's worth noting the wealth of data and research compiled in this review, which should help inform discussion and debate about tolling in Sydney for some time.

42 recommendations were made, and I wont repeat them all in detail here. 

However, a key part of the review work was to model the impacts of models of reform that were presented. It's critical to understand that the report recommends "moving towards" the Network Toll Restructure and Reduction model, not necessarily the details of that model exactly, but does not recommend the Network Toll Restructure Model.  Therefore, I will focus on the former.

These models are:

• Network Toll Restructure model: Introduction of standardised network tolls and including application of two-way tolling; and

• Network Toll Restructure and Reduction model: This uses revenues generated from two-way tolling, peak pricing and other sources to reduce tolls where appropriate. A declining distance approach with fixed infrastructure charges is proposed.

The effect of the latter was modelled as meaning:

• 78% of motorists are the same or better off, 17% would pay $3 + more per trip.

• Main losers are those using the Sydney Harbour Crossings

• Western Sydney motorists get some relief as longer trips are reduced in cost

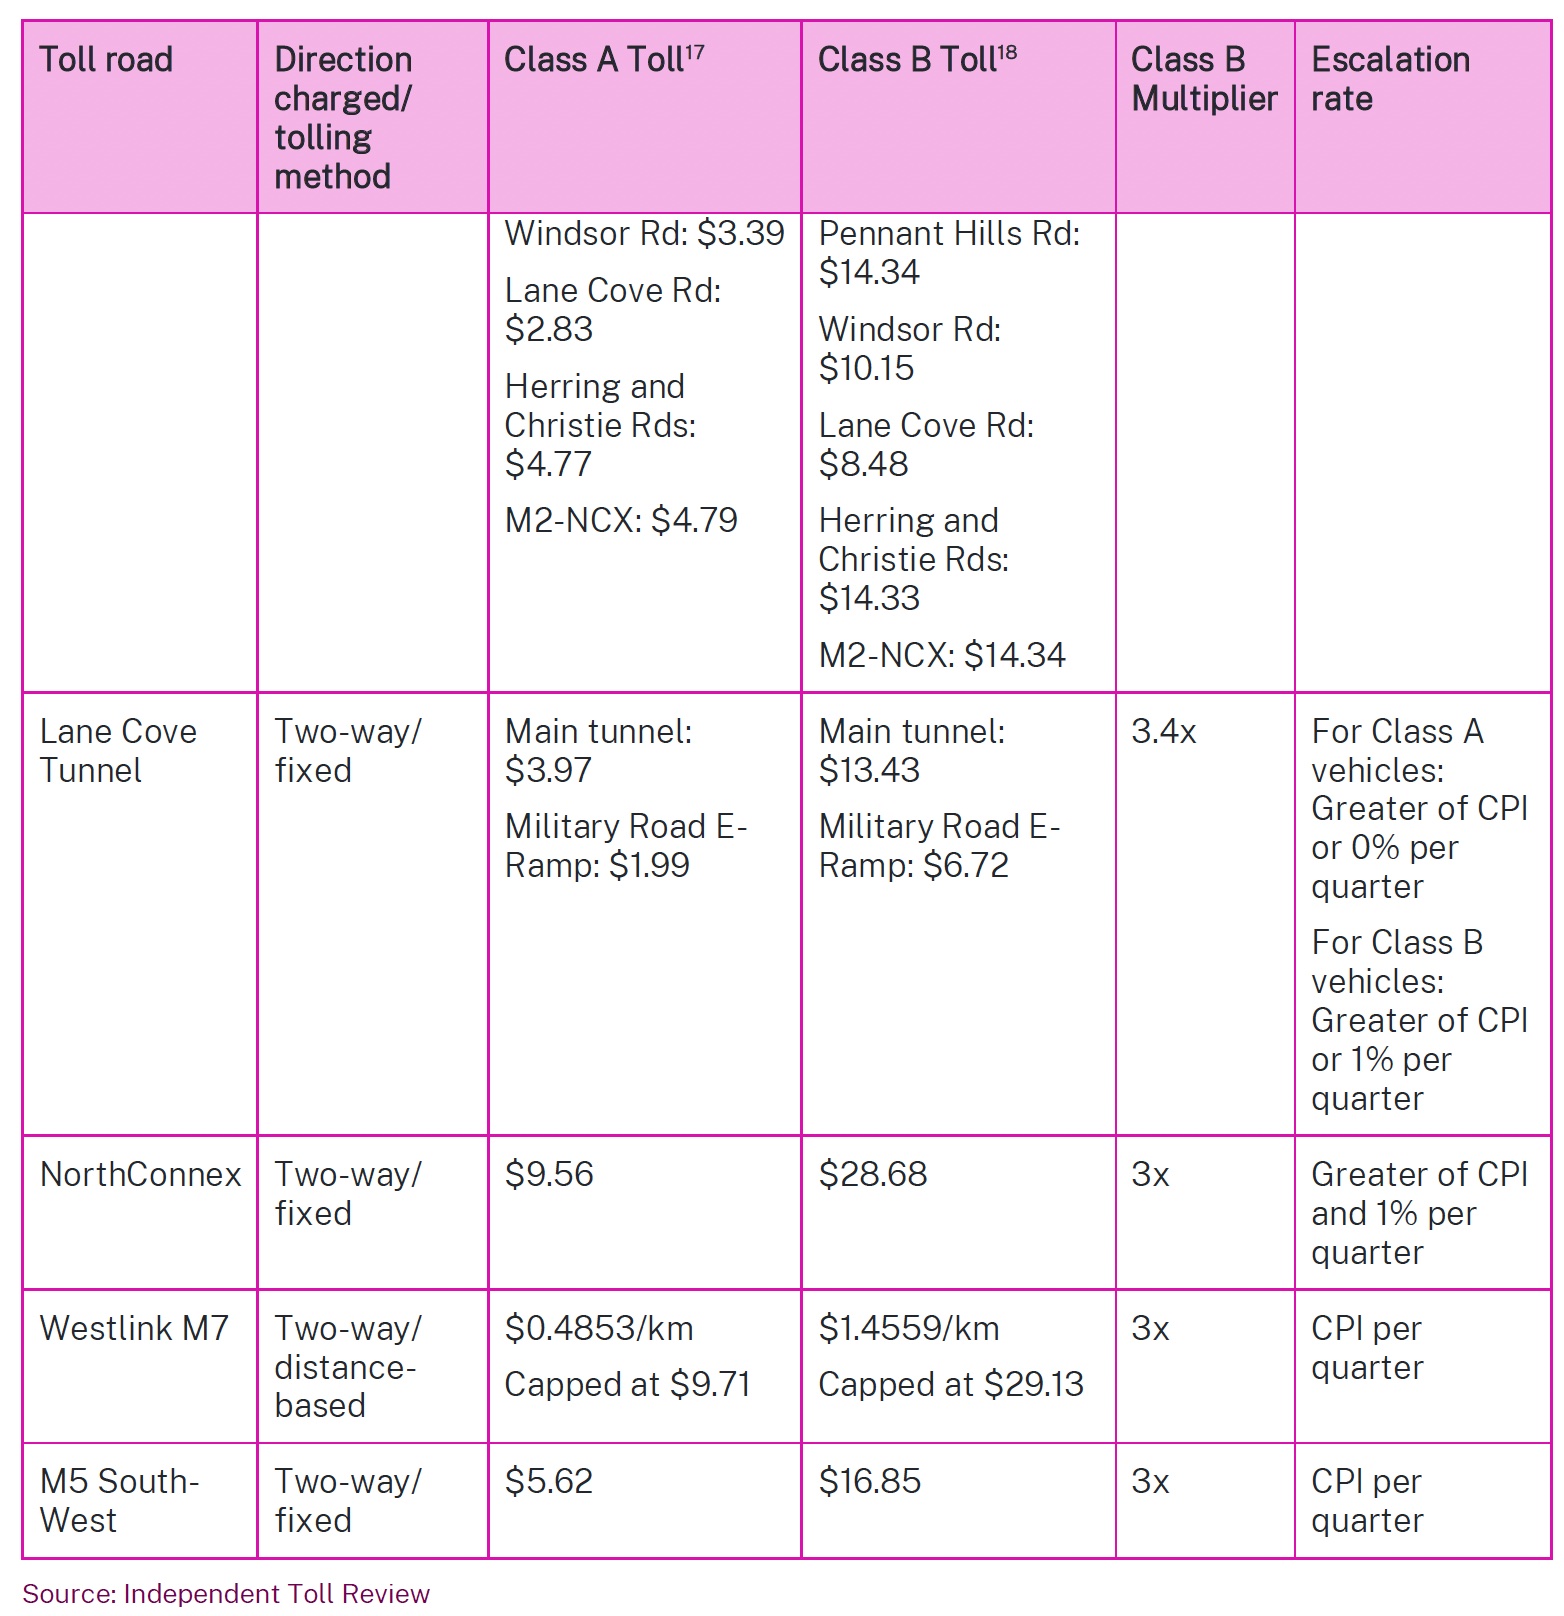
The following table lists the current tolls in Sydney (all in Australian Dollars ~ US$0.66-A$1.00:


As you can see the basis for tolling varies between being two-way or one-way, fixed or distance-based, with rates for different classes of vehicles varying considerably between toll roads, and the basis for adjusting tolls varying as well.

The proposed new structure is as follows:


This is for Class A vehicles only for simplicity in illustration, but would have a consistent toll distance rate, with infrastructure rates that reflect fixed costs for those roads. The declining percentage means that every 4km the per/km distance rate declines 15%.  The effect is to make some shorter journeys more expensive, and almost all longer ones cheaper.

The following table indicates what the modelling of the Tolling Review suggests would be the distribution by trip distance of the "winners" and "losers" of reform. All those travelling longer distances would be better or no worse off, whilst about 40% of shorter (<10 km) toll road trips would be more expensive. 


The difference in average toll for a car would be to reduce from $9.02 today to $5.43, a drop of 40%. The effects on the network are seen in the following map, depicting traffic increases and decreases on the tolled and untolled network. It would increase traffic on the M2, M4, M5 east and south west and M7, as well as River Road, Victoria Road and James Ruse Drive (as traffic either avoids the northbound Harbour Crossing tolls or queues to use the M4 more intensely). 


It's striking that the obvious impacts on reducing traffic are on the Harbour Crossings and Eastern Distributor, as introducing northbound tolls on the Harbour Crossings and southbound on the Eastern Distributor sees some redistribution of traffic to the west, primarily on the untolled crossing at Iron Cove Bridge and Gladesville. There is also reduction on some streets in the CBD and some parallel routes to the M5, as lower tolls make some toll roads more attractive that local streets for some drivers. The M4 and M5 in particular see much higher traffic volumes. It's unclear the impact on congestion overall, as this did not include any peak/off-peak pricing on a network basis.

This table produced with the press release accompanying the Independent Toll Review (PDF) illustrates the effects on some toll trips:


The Toll Restructure and Reduction scenario has significant impacts on all of these examples, notably halving the cost to drive from Campbelltown to the CBD, but more than doubling the price from North Sydney to the airport. 

Before summarising the other recommendations, it is worth going over in some detail the proposed tolling principles (the first set of recommendations).

Tolling principles

These principles are recommended to guide policy measures to reform tolling of existing roads and should inform the implementation of tolling on new roads.

The Tolling Review considered the set of tolling principles agreed in 2014 which were as follows:

1. New tolls are applied only where users receive a direct benefit. 

2. Tolls can continue while they provide broader network benefits or fund ongoing costs. 

3. Distance-based tolling for all new motorways. 

4. Tolls charged for both directions of travel on all motorways. 

5. Tolls charged reflect the cost of delivering the motorway network. 

6. Tolls take account of increases in expenses, income and comparable toll roads. 

7. Tolls will be applied consistently across different motorways, to the extent practicable, taking into account existing concessions and tolls. 

8. Truck tolls at least three times higher than car tolls. 

9. Regulations could be used so trucks use new motorway segments. 

10. Untolled alternative arterial roads remain available for customers. 

The review found that these were rather general and didn’t include some key issues, such as the proportion of costs that should be recovered from tolls relative to taxpayer funds. There was little recognition of the need for tolls to vary by time of day, plus although some of the principles (tolling in both directions) are valid, they were not always applied (see the Harbour Crossings and Eastern Distributor).

The review proposed a set of modified principles with one set about the level and structure of tolls and another on consistency with competition policy.

Proposed New Tolling Principles

On the level and structure of tolls:

• Toll setting should be guided by the objectives of efficiency, fairness, simplicity and transparency. 

• Tolls should have regard to the costs associated with the provision of toll road services as well as benefits. Declining distance-based tolls are consistent with the principle and have efficiency and equity advantages over fixed distance-based tolls or variable zonal distance-based tolls. 

• In general, it is appropriate that beneficiaries pay for toll roads, for example, where benefits flow to the broader community then government contributions are appropriate. The extent of cost recovery achieved through tolls should reflect the extent to which a toll road’s benefits are enjoyed directly by motorists. 

• The process for setting tolls should be transparent to the public to promote understanding and allow for informed comment. 

• The methodology for determining tolls should, so far as possible, be applied consistently across the entire network. 

• Tolls should allow toll road operators to recover their costs incurred in financing the construction of the toll road including an appropriate (i.e. risk adjusted) return, and efficient operating and maintenance costs where relevant. It may be appropriate to apply specific charges to individual parts of the network to allow for cost recovery, for example infrastructure charges to cover the additional costs associated with constructing tunnels or bridges. 

• Tolls should not be set at a level which would allow excessive, monopoly profits, or inefficient cost levels to prevail over time. 

• Maintaining flexibility to adjust tolls over time in response to demand and supply changes is important. 

• Toll setting should take into account fairness as well as efficiency considerations, bearing in mind that other more direct policy approaches may be preferable forms of intervention in relation to fairness. 

• The different vehicle categories for tolls should balance impactor pays (the extent to which vehicles impose costs on the network and other users due to their weight and size set against the costs imposed by such vehicles on ancillary roads) and beneficiary pays considerations (a higher willingness to pay for travel time savings). For example, under this principle setting higher tolls for heavier and larger vehicles is consistent with efficient tolling. 

• The structure of tolls should be simple enough to be readily understood by users and avoid creating perverse incentives for the use of the road network. Inconsistent approaches to the tolling of toll roads can cause distortions to traffic flows. 

• Tolling information should be communicated in real time to inform customer journeys and enable improved decision-making.

On consistency with competition policy:

• Competitive pressure should be harnessed when setting tolls and assessing concessionaire bids (competition for the market) and when regularly reviewing tolls (competition in the market). Bidding for concessions should focus on ensuring tolls are set at competitive levels. 

• Unsolicited proposals for toll road extensions should not be considered in isolation of the possibility of first modifying tolls to better manage traffic flows. 

• Restrictions should not be imposed on the use of any road or public transport in order to enhance the financial viability of a toll road. 

• Tolls should only apply where motorists have reasonable and effective untolled road options, including arterial roads, or public transport alternatives, except where community benefit may necessitate restriction on access to alternatives. 

Other recommendations

Moving to network tolling: The core recommendation is to change the current ad-hoc setting of tolls by individual concession (and the State), to a more coherent and consistent approach. The key recommendation is to have declining distance-based tolls, so that the first two kilometres are charged at a higher rate than the next two and so on.  This is for fairness, but also efficiency to recognise the cost imposed on other users of using toll roads for shorter trips, and disrupting traffic flow.  Network tolling should mean some reductions in tolls, through measures like implementing two-way tolls on one-way toll roads, and more use of peak tolling to lower tolls off-peak. Moving to network tolling should help with steps to phase out or reform toll relief, and how to progress this over time. Other options to lower tolls includes extending toll concessions.

Using pricing to influence demand: Going beyond tolling as an infrastructure cost recovery measure, is to use peak and off-peak pricing, with an initial focus on trialling peak pricing for the freight sector. This is both to reduce congestion at peak times, and to encourage better use of spare capacity off-peak. Included in this recommendation is dynamic pricing, which by the conventional definition is not a good idea in this context (although reviewing peak/off-peak pricing more frequently than annually IS a good idea). 

Updating vehicle classifications and charges: Having uniform classifiers and consistent multipliers for heavy vehicles are the key recommendations, along with exempting public bus services from all (not just some) toll roads.

Expanding toll coverage: Applying two-way tolling on the Sydney Harbour Crossings and Eastern Distributor is the obvious step (and one that has generated understandable controversy in isolation). More strategically, the review recommended evaluating the entire motorway network to see if untolled sections should be tolled (reducing tolls on other sections) or if tolls should be removed from some sections. It seems likely that this will be difficult to sell politically.

Initial assessment of toll reforms: Implementation of the reforms should be carefully monitored with frequent modelling to ensure results meet policy objectives.

NSW Motorways: The review recommended establishing a new entity called NSW Motorways, intended to strengthen governance and accountability over NSW toll roads in order to improve outcomes and transparency for motorists. It would work with concessionaires to set network tolls and adjust them working with concessionaires. It would take over the E-Toll retailing business of Transport for New South Wales and have a focus on innovating to improve the tolling experience in the state. It could also manage future toll roads and contract managers for those toll roads, and bring existing public toll roads within its operations.

Concessionaire negotiations: The Review recommends that the Government negotiate with concessionaires to implement network tolling by the end of 2024 and if not achieved, use legislation to advance it. This raises obvious concerns about legislating over the contracts the state has with concessionaires.

Independent oversight of toll setting: The Independent Pricing and Regulatory Tribunal (which is already price regulator for water, public transport and local government services) should also have oversight for toll rate setting. It should work with NSW Motorways and Transport for New South Wales to monitor prices, including the financial and traffic impacts of network tolling, toll relief schemes, the need for and operation of time-of-day pricing and concessionaire performance. 

Legislative package for toll setting: Essentially a recommendation to legislate over concession agreements if necessary to implement network tolls. This should include a Revenue Adjustment Mechanism so revenues can be “appropriately” shared.

Competition measures: These recommendations seek more competition in future concessions and a long-term view on competition with procurement of future toll roads. Concession periods should be set based on public interest considerations, including competition. Competitive tendering should be favoured over unsolicited proposals. Roaming fees (across retail toll providers) should be regulated.

Transparency for motorists: Motorists should be able to see past and projected future toll road spending.  More information should be provided for trip-planning online and via apps, as well as better signage to inform motorists of toll road prices before they make a decision on whether or not to use a toll road.

Tolling customer advocate: NSW Motorways should have a tolling customer advocate function to consider and manage customers complaints, influence improvements to systems, processes and legislation to minimise future complaints and improve compliance. It should manage awareness and education campaigns, address new “pain points” from the transition to network tolling, and publish reports on the implementation of toll reform. If a toll debt is disputed, debt recovery action should be suspended while the dispute is being addressed.

Industry ombudsman: Proposes that NSW, Victoria and Queensland require toll operators to belong to a statutorily approved independent dispute resolution scheme.

Toll notices: These should be simplified and modernised, calling them “invoices” and removing administration notices, but adding late payment fees to incentivise early payment. Information provided should be user-centric, informing them of the most common reasons for non-compliance (flat tag battery and number plate not linked to an account) so motorists can address such issues to avoid a repeat of unpaid tolls.

Debt recovery:  Reform criminal enforcement so there is only one offence per trip and clearly identify if it applies to the driver or the registered vehicle. At present debt is owed by the vehicle’s owner, but it may be appropriate for that to be the driver in some cases. For civil debt recovery, find ways to improve the accuracy of contact information for registered vehicle owners. Noting that debt collection agencies seem to be able to find debtors easier that toll road operators. Toll road operators should develop and publish customer charters

My thoughts

This is a weighty report, and a lot of thought has gone into it.  The reforms proposed might be categorised into three areas:
  • Rate setting/tolling policy
  • Business rules
  • Competition
  • Governance
The most fundamental part of the review is the recommendation to take a network approach, and to apply a declining distance based tariff with an infrastructure fee layered on top of it for the higher capital cost toll roads. There is merit in taking such an approach, albeit it is obvious the biggest challenge is doing this whilst ensuring concessionaires are not disadvantaged, and consent to the changes. The "sword of Damocles" of regulation may be there, but it is not one the NSW Government will want to enforce, as it is likely to make any future PPPs more expensive (as it would have an impact on investor confidence in contracting with the NSW Government).

Two-way tolls and having consistent vehicle classifications and multipliers all make economic sense, but it will be difficult to convince motorists that pay one-way on the Sydney Harbour Crossings that they should pay in both directions, without getting anything for it. Other than by halving existing tolls (so they are split by direction), which will likely exacerbate AM peak congestion, it seems unlikely that this will be able to be implemented due to public resistance, although if it were focused on managing demand (and moderating tolls for the Western Harbour Crossing) there might be more tolerance for it.

Certainly the distributional impacts of tolls in Sydney fall greatest on those in the West, so it is understandable why there is some emphasis in improving conditions for motorists there. I note that significant cutting tolls from Campbelltown to the CBD, a route which has a frequent commuter rail service, might have negative impacts on congestion if the modelling doesn't take into account the risk of modal shift from rail to driving, although the cost and availability of parking is a significant deterrent.

The biggest challenge is going to be getting agreement from Transurban to advance these proposals. This is only going to happen if it can be convinced it will be no worse off, not just today, but over the duration of each concession, because each concession has investors (Transurban does not own 100% of all of them) expecting consistent returns. The willingness to do this is likely to be limited, as it requires forecasting changes in demand for several decades out.

The proposal to enable peak/off-peak tolling is likely to have the greatest impact on congestion on the one-hand, and underutilised capacity on the other, noting that for concessionaires, underutilisation is not a problem but rather maximising yields. If there is a public policy reason to reduce tolls off-peak on some roads, to remove traffic from other roads, this may justify a subsidy, or better yet, justify peak pricing to offset it. 

What all of this suggests is that the proposal to change governance, by creating NSW Motorways, to undertake the analysis and modelling needed to advance negotiations with Transurban, will be important. Assuming the NSW Government is not willing to regulate over concessions, it will need to be able to model the impacts of a range of pricing policy options on each individual concession, and to creatively identify options to ensure that public policy objectives are achievable (reducing congestion, better use of toll roads off-peak) alongside making sure concessionaires are willing, to commercially, to accept changes to their concession agreements.  It is appropriate to set up NSW Motorways in any case, as a road regulator which applies to state toll roads (there are two more being built now on top of the two existing Sydney harbour crossings), and which could be extended to cover a future road user charge...

The Review does allude to the wider issue of how motor vehicles are charges for road use across the network in NSW, and the need for some form of road user charging for EVs. Ultimately, there may be scope for more direct user charging across all roads, but given the Vanderstock decision at the High Court of Australia, that looks likely to be led by the Commonwealth Government. At the very least, the NSW Government should be thinking strategically about tolling in that wider context. It is not that road user charging will replace tolling anytime soon, but if there is to be a shift towards distance based tolling across the board, it should not be inconsistent with applying some form of per kilometre charging for vehicles on all roads. 

On the business rules side, the proposals around debt recovery, transparency for motorists and an industry ombudsman are all good from a consumer protection point of view.  None of this should be particularly controversial.

Given the role of Allan Fels it should not surprise anyone that competition has been a focus of this review. The dominance of Transurban should give cause to seek to diversify the profile of future concessions, but the retention of retail competition is also important. Bear in mind the main competition for toll roads are the untolled roads (and for a small subset of users, public transport on some corridors), and although it is flawed, toll roads do have a form of price control over price increases (albeit it effectively means prices increase by inflation).  However, competition can never really be addressed whilst other roads are priced so indirectly, through fuel tax and fixed charges like motor vehicle registration fees. Perhaps the most effective way of enabling competition for future toll roads is either for such roads to be state owned and concessions issued for operations, or for future concessions to have tolls set by independent regulation.

Finally, although the political will is hardly likely to exist for it, there is likely to be sense in at least considering implementing congestion pricing in the form of a CBD cordon in Sydney in parallel with such changes. Such a cordon could be used to moderate tolls as well as better manage congestion on traffic towards the CBD, but that was outside the scope of this review.

The response

The Government response so far is through this press release, which is not really a response as of yet. According to The Guardian, Transurban has said it wants to take a corridor based approach and does not approve of the full network approach.  Roads Minister John Graham also suggested that taxpayers might pay concessionaires to implement some of the recommendations, which is a good idea, if it results in net benefits to consumers and the economy (noting that it could reduce the cost of existing toll relief schemes if tolls can be reduced for some customers).

The full response will not be clear for perhaps a few months, and it seems unlikely that all recommendations will be accepted. However, there is a strong case for more consistency in tolls across Sydney, and despite the unpopularity of two-way tolls for the harbour and peak tolling, the merits of being able to spread demand more efficiency are likely to be high.

What needs to be behind any reforms are consistent principles and objectives. Discouraging short trips on toll roads is likely to result in more efficient use of the network, declining distance based tolls makes sense up to a point, but the merits of high toll costs for long distance travel come from the signals they send for land use and modal choice. 

There have been enough toll reviews in recent years, as my first post on this topic showed (and I was involved in one of them myself). I sincerely hope the NSW Government acts on much of what this one recommends.


Wednesday, 24 July 2024

"Motorists First" - Findings of the Independent Toll Review for the NSW Government - Part Two: The Findings

Following on from my previous post, this is a listing of the 16 findings of the review. Not the recommendations, but the findings. I have included some of my own comment on these at the end of each finding. Generally the findings are fair, although I think some of them are repetitive and essentially different sides of the same point. The findings have a strong consumer interest element to them, which is unsurprising given it was led by Allan Fels, but there is also some discussion around public policy implications and a bit around markets and delivery of services. Again it reads a bit like an ACCC series of findings, unsurprisingly.

For me, the main points are the lack of coherence around toll rate setting and structures, the inflexibility to apply time-of-use based pricing to better manage congestion and demand, and the poor policy responses to the current structures.  The dominance of Transurban is valid in the toll concession process, but with the presence of E-toll, its retail market share is not monopolistic. Future envisaged toll roads are not intended to be undertaken as PPP concessions, indicating a willingness to take a different approach, although it should be possible to proceed with PPPs without the restrictions and constraints (including the toll rate escalators) implemented in previous years.  Following this article will be one on the recommendations and what I think of those.  However, for those outside NSW, the main benefit of this report is on lessons to apply elsewhere around toll rate setting, PPP contracts and taking a strategic network view, rather than an ad-hoc approach to separate major projects. 

The structure of the findings is a summary of the findings from the report, followed by my brief comment.

The findings

1: The process for setting tolls has been flawed: Largely because governments determined them in advance of PPP concessions, rather than using competition in procurement to incentivise bidders to propose the lowest tolls needed to fund the roads. Long concession periods and higher than inflation cost escalators mean tolls in early years are lower than they should be, as the cost of the infrastructure is pushed towards future users more than early users.  Efficient in road and toll operations almost entirely benefits owners of concessions and is not reflected in lower tolls. Comment: Ideally tolls should be proposed by project bidders or proponents and be subject to competitive pressure, and rigorous public sector scrutiny. It is worth reviewing the merits of allowing tolls to increase above CPI if costs do not do so, but not there is also no scope for tolls to reflect actual demand. Rigid concession conditions around tolls affect the ability for future tolls to be able to address distortions in pricing between tolled and untolled roads, and changes in demand across the network.

2: PPP details relating to toll setting are not publicly disclosed reducing information available to assist in public understanding: Commercial confidentiality claims around PPP agreements limit this information, and consequently increase public disquiet about toll rate setting. The Review noted that Base Case Financial Models are confidential and commercially sensitive, but said returns from PPPs are “generous”. The Review cannot publish the differences between actual revenue and model forecasts because of this confidentiality, making it difficult to assess whether tolls set are too high and whether excessive profits are being generated from toll concessions. Comment: Future concessions should enable regulatory oversight of the differences between actual and forecast revenue. A careful balance is needed between incentivising PPPs sufficiently and not enabling rent-seeking behaviour.

3: Toll road users bear a disproportionately high proportion of the cost of toll roads: The key issue is when toll roads bypass the untolled network and generate significant local amenity benefits. The Review noted the Cross City Tunnel (which provides a bypass of inner Sydney between east and west) which brings significant benefits to surface traffic, including property owners and pedestrians, but was expected to be fully funded by the users of the tunnel. There is a case for those others benefiting from the project to contribute towards its costs. Comment: Toll roads offering significant local amenity improvement, due to removal of traffic and enhancing of property values ought to be partially supported by revenue generated from surface traffic (through network charges such as fuel taxes) and property taxation from property owners. It is clear the Cross City Tunnel in Sydney is underutilised due to its high toll structure.

4: There is no overall system of tolls: Tolls are all set in isolation of each other, and although they could be set to send price signals to optimise the use of road infrastructure they are not designed to do so. The complexity of tolls as they are, including toll relief schemes, untolled motorway sections (which are often used by many motorists paying tolls on other sections).  Comment: From a network perspective, tolls in Sydney send inefficient price signals that distort behaviour and do not encourage efficient network use. For example, overnight toll prices are far too high and ought to be set to remove traffic from surface streets whilst peak period tolls are often too low, and should be priced to encourage time and modal shift. There are no effective means to enable this.

5: The lack of a unified tolling system creates complexity, inefficiency, inequities and unfairness: With different vehicle classification systems and toll regimes, similar trips are priced differently across the network. Roads with similar levels of service are priced differently. Smaller trucks are in some cases charged the same as larger trucks, discouraging them from using some toll roads. Comment: As above, there should be more efficient pricing applied by location, distance and time-of-day and vehicle class. More standard pricing across the network, unless particularly costly parts of infrastructure are being used, would be rational and efficient.

6: Tolls are too rigid and locked-in for decades without options for review:  No other sector of the economy sets prices for such a long period, certainly no other transport mode. This increases perceptions of unfairness over time, as prices rise faster than inflation. The Review reports modelling that around A$123 billion in tolls will be paid between 2024 and 2060. With no processes or means to review tolls during those concession periods, it raises serious questions as to why it is justifiable to have prices set for well over a generation through contract between the private sector and state government. Comment: Concessionaires like guaranteed toll levels and escalations, but no other investments in the private sector guarantee such revenues without regulatory oversight (see energy and water utilities which are subject to such oversight). This suggests that future PPPs have provision for regulatory oversight of pricing at regular intervals.

7: On most toll roads, time-of-day tolling is not used:  At off-peak periods many toll roads are heavily underutilised, and at peak periods several can be highly congested. Pricing should enable better utilisation of the infrastructure. Comment: Generally, there are wider economic benefits in enabling better use of tolled infrastructure, especially since most of it has natural monopoly characteristics and there are some amenity benefits in enabling it.  However, there is limited elasticity of demand off-peak, in that lower prices will result in lower revenues (as additional traffic is unlikely to offset reduced prices), although at peak times higher tolls that reflect demand profiles should improve congestion on a network basis and encourage modal shift. There are considerable merits in enabling time-of-day pricing, subject to regulation, in ways that do not undermine concession net revenues, but significant improve outcomes for the transport network. 

8: The financial impact of tolls is greatest in Western Sydney: Western Sydney suburbs have the highest proportion of motorists paying over A$60 a week on tolls, reflecting the extent of tolled infrastructure in the West and the lack of useful alternative routes. This arguably affects access to employment and other opportunities for residents in those suburbs. 

9: Transurban’s profitability has not been excessive in recent years, but its NSW toll road portfolio profitability is likely to increase over time in line with traffic and toll rate escalation, and declining construction costs: Sydney generates 50% of the toll revenue for Transurban, but its returns are not excessive when considered against the Weighted Cost of Capital. However, it is expected that profitability will row in future years. Comment: This is critically important, as it is important to ensure that Transurban isn’t extracting excessive rents from Sydney road users. However, it also suggests that the toll rate setting system for future concessions should not enable continued increases above inflation.

10: The level of tolls appears to be higher than necessary and desirable: This is in part, counting earlier points as follows. There was no competitive bidding for PPPs on the basis of toll price, concession agreements allow relatively high returns for multiple reasons including a regulated monopoly price safe from competitive challenge, incentives for efficiency are largely captured by concessionaires (and not shared with users). Toll roads are relatively free-flowing and potentially underutilised (indicating tolls are certain times are too high) and motorists perceive tolls as too high. Most of those surveyed who claimed tolls are too high tend to use alternative non-toll routes or reduce frequency of non-essential travel. 15% use other modes, but nearly 40% do not change behaviour (but pay the toll). Comment: There is clearly a distortion in travel between tolled roads and untolled roads essentially because of underpricing of untolled roads. Surveying the public about tolls is likely to result in an answer that many people think tolls are too high, but the real evidence is that the tolled network has much less congestion, on average than the untolled network. Many complain about tolls but still pay them, but that does not mean that tolls are not too high, but it does mean that this is overplayed. Toll roads take up land, and are high capital cost assets and arguably it is fair they generate a return on capital (even if this isn’t what explicitly happens with other roads). However, the negative externalities of pricing only part of the network are not insignificant, and there is a strong case for enabling time-of-use pricing.

11: Transurban has a dominant market share in the current provision of toll roads in Sydney:  Although this is clearly the case, there is competition from untolled roads and other modes. Restrictions on Transurban include the limits on toll rate increases and the conditions on maintaining network quality during concession periods. Comment: Transurban has been commercial adept in expanding its presence in the market, but the “market” itself has entirely been driven by the State Government issuing concessions and the conditions it sets for those. The presence of the state account manager adds significant competition in terms of customer service, for “some” services, but concern over Transurban’s dominance is within the control of the State Government for future toll road concessions and in future regulation of them.

12: Transurban has been dominant in the NSW market for acquisition of toll road concession contracts: This is due to factors, such as its experience in bidding, the economies of scale of its existing operations and its access to in-house data on traffic and in modelling.  It’s noted that of the four motorways under construction in Sydney today, two wont be tolled and the other two will be state-owned toll roads. Comment: This is essentially a repeat of the previous finding, and what matters is what impact it has on public finances, motorists and the economy. That hasn’t been explained clearly.

13: The significant position of Transurban in the toll retailer market could adversely affect competition for tolling concessions: Until 2019 there were four toll road retailes, but Transurban acquire two of them. Now it is Linkt (Transurban), E-Toll (State Government) and Eastlink (a toll road in Victoria) that hold the entire market, with Eastlink’s presence essentially only for a handful of vehicles that hold such accounts in Victoria visiting Sydney. Barriers to entry are not seen as significant, and clearly the presence of E-Toll makes a difference to Transurban’s performance in the market. Comment: There is a “could” here significantly diluted by the presence of E-Toll, but there aren’t enormous barriers to market entry and future concessions and toll roads should be open to more innovative solutions in providing retail services. This could include the growing mobile phone based suppliers, but longer term the inevitable implementation of RUC in Australia should see providers of such services also being able to supply toll retail services to their customers (e.g. telematics service providers for heavy vehicles). 

14: Current tolling information fails to adequately enable, inform, and educate motorists thus reducing user empowerment and efficient decision-making: There is no “one-stop” platform for motorists to obtain all tolling information (including available rebates) and undertake trip planning in a way that is easy to use. Signage about toll rates is inadequate to give motorists sufficient time to adjust route choice. Retail toll platforms do not allow motorists to project future toll usage. There is little understanding as to how tolls are calculated, or understanding about toll administrative charges, and what revenues are used for on non-PPP toll roads. There is also insufficient information about the rights and responsibilities of toll road customers. Comment:  This is true, although there is nothing stopping there being such an app or platform to do this, other than the lack of commercial interest in doing so.  Signage should better enable route choice, and even could compare travel times by tolled and untolled road, although this would have to be the responsibility of the public road controlling authorities. 

15: Toll reform is preferable to toll relief: The current toll relief schemes are inadequately targeted and underutilised, in part due to overly complex administration. Toll relief is not financially sustainable given the existing pattern of toll escalation and limitations on the availability of government resources to fund relief:  This is focused on the M5 toll relief scheme which is confined by geography, does not have processes for review. It appears to be politically entrenched and is likely to have significantly affected transport and land use decisions along the M5 corridor. This and other toll relief schemes are blunt and likely to be financially unsustainable, and likely to primarily benefit higher income earners. It would be preferable to reform tolls more widely. Comment: Clearly the current toll relief schemes are inefficient ways to address public concerns about toll rates, and it would be much preferable to phase it out and reform the toll system more widely. 

16: Concessionaires are an unintended beneficiary of the current approach to toll relief. Increased traffic and patronage of toll roads, through induced demand created by toll relief, directly benefits operators by increasing their revenues: By subsidising tolls, toll relief effectively benefits concessionaires by subsidising demand for their facilities. It is not enough to generate funds beyond agreed levels that would require upside sharing with government, but is enough to benefit Transurban.  Comment: This highlights the inefficiency of toll relief as a subsidy from other road users and taxpayers to concessionaires and the beneficiaries of relief.

Monday, 22 July 2024

"Motorists First" - Findings of the Independent Toll Review for the NSW Government - Part One: Background

 This is the first in a multi-part series about the epic toll review.

“Motorists First” (PDF) is the title given to the latest report on tolling in Sydney. Led by Professor Allan Fels. Fels is best known as having been Chairman of the Australian Competition and Consumer Commission between 1995 and 2003. The focus of his career has been on breaking monopolies, and he took this opportunity of leading the Independent Toll Review for the Minns’ Government in New South Wales to try to do the same to Transurban – which has a stake in most of the toll roads in Sydney.

The review was announced in July 2023, three months after Labor won the state election, but it follows a long line of reviews of tolling in New South Wales (by which I mean Sydney as there are no toll road outside the greater Sydney metro region).  The review posted this handy list of the reviews undertaken by multiple NSW state governments. 

Major toll road openings and New South Wales tolling reviews over 21 years

Why so many reviews? Sydney has one of the most extensive toll road networks of any cities globally, although I have yet to see any detailed research to identify whether it has the biggest tolled road network of any city (Santiago, Chile has quite a network).

Most people are aware of the Sydney Harbour Bridge, opened with tolls in 1932 and still tolled, but much of Sydney’s urban motorway network has been funded through tolling and financed through a patchwork of PPPs.  The latest review notes that of 320km of motorways,156km are tolled. Although there are alternative routes, it is slow and inconvenient to drive from the north or south of Sydney towards the airport or city centre without using toll roads. 

Sydney's tolled and untolled motorway network

Untolled sections were mostly built in the 70s and 80s, whereas the tolled sections have been built since then, with more under construction (the Western Harbour Tunnel and Stage 1 of the M6, which eventually will bypass Sydney’s southern suburbs towards Wollongong). 

The 382 page review has a lot of information in it, and so is worth pouring over for those who are interested. Here are some highlights that I found of interest:

• Only around 4% of journeys (using any mode) were made using toll roads, and 7.6-8.8% of car journeys are undertaken using toll roads at least once.
• There are 10 PPP concessions and 2 state government owned toll roads, Transurban has some shareholding in all of the PPPs (ranging from 50-100%).
• 56% of the toll retail market is held by the state operator E-toll, and 44% by Transurban operator Linkt. This suggests that a majority of toll road users prefer having the state as account manager, not the operator of most of the toll roads (only the Sydney Harbour Crossings are not at least partially owned by Transurban) 
• Westconnex has the biggest proportion of toll road traffic and revenue.
• Toll rates on all routes, except Westlink M7 and Westconnex are point charges (M7 and Westconnex have flagfalls plus a per km rate)
• Only the Sydney Harbour crossings have prices that vary by time of day (A$4.27 peak, A$3.20 interpeak and A$2.67 off peak), but there are only tolls in one direction on the crossings (and the Eastern Distributor).
• Toll escalation factors for the PPPs tend to be based on the greater of CPI or 1% per quarter.  

The review includes this handy chart describing the ownership and key suppliers throughout the supply chain for all of Sydney toll roads:

Sydney toll road ownership/supplier distribution

What's the problem?

What’s the problem?

Fundamentally there are public and political concerns that tolls are incoherent and unfair, largely because each toll concession has seen tolls set that reflect the cost of supplying each individual segment of tolled road at the time it was built. This has resulted in a network that isn’t priced like a network, but priced ad-hoc. The result of this has seen a range of interventions by the state government which are arguably also heavily flawed, including the M5 Cashback scheme, which gives refunds to regular users of that toll road, and was set up entirely for political reasons. That scheme alone costs around A$127m per annum. 

What did the Review find?

16 findings were published by the review, which I will summarise in my next post...